As a life insurance agent, I’m accustomed to talking to people from all walks of life. Amazingly, no matter what a person’s background or where they currently are in life, many prospects make the same mistakes when looking for a quote or trying to buy coverage.
By mistakes, I mean the process may take longer, you may not get the coverage you want, and you may inadvertently get denied even though you should qualify.
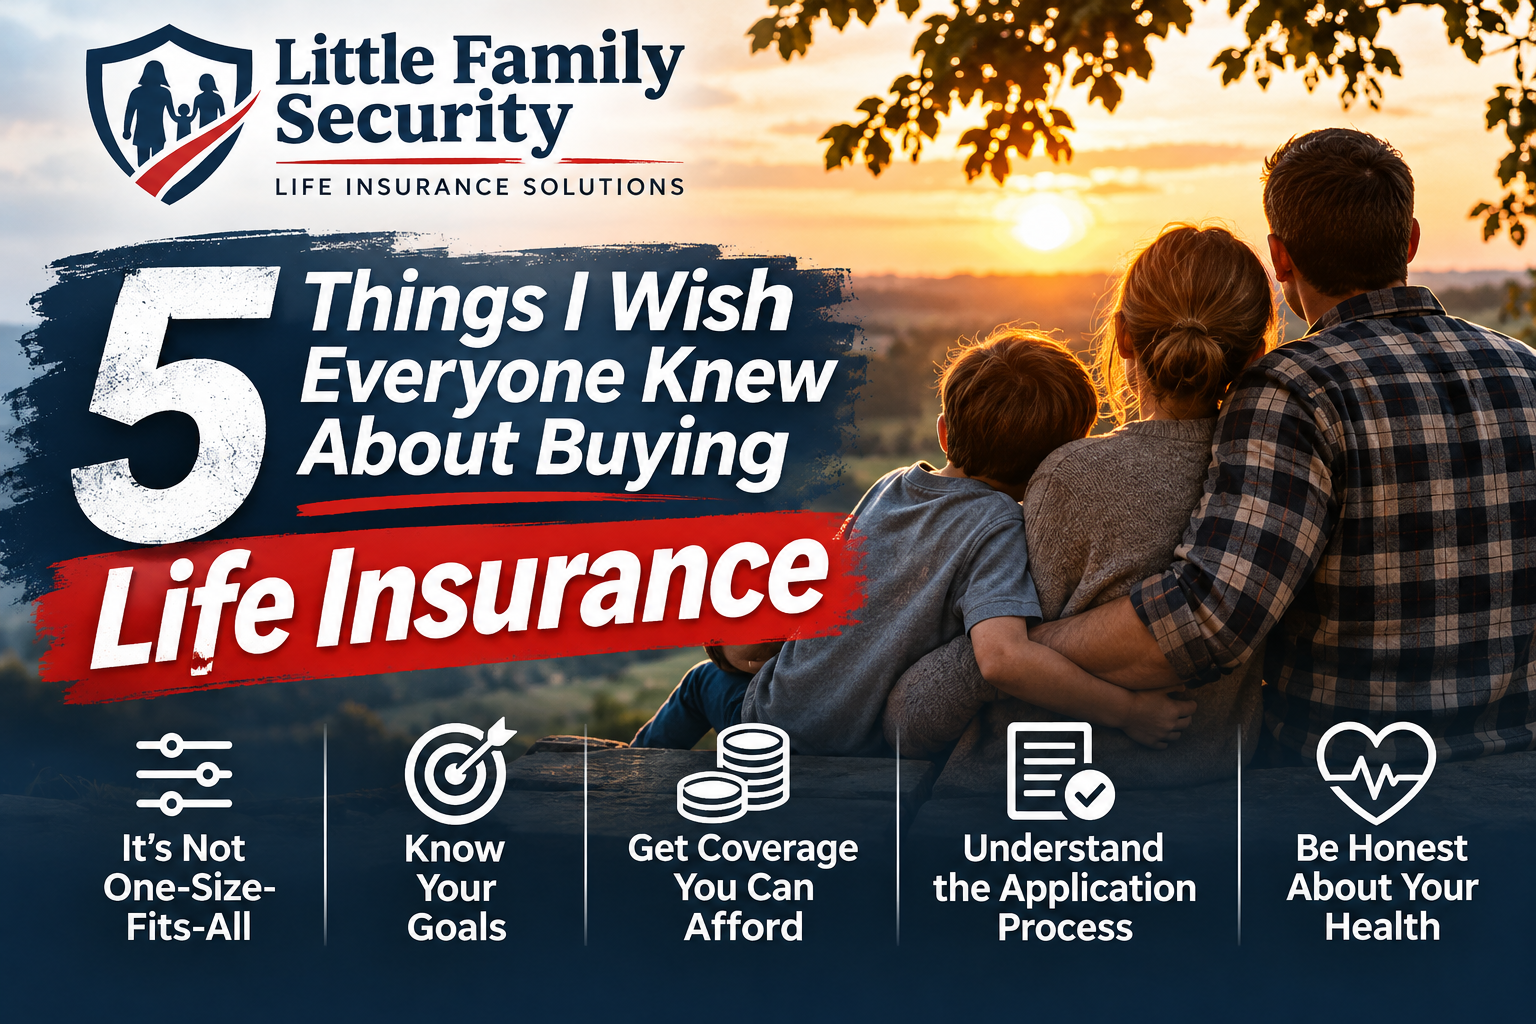
To ensure that you don’t make those same mistakes, and to make the process smoother, here are five things you should know the next time you talk to an agent in person, on video, or over the phone.
It Is Not a One-Size-Fits-All Approach
If I had a dollar for everyone who asked me, “How much is life insurance?” I’d be a rich man. Unfortunately, this question cannot possibly be answered without a little information gathering.
Imagine if you went into a clothing store and asked, “How much are pants?” The clerk would look confused before asking, “What kind of pants and what size do you wear?” It’s the same with life insurance.
To accurately provide you with a life insurance quote, your agent needs vital information. Life insurance premiums are based on age, health, and lifestyle.
The older you are, the more expensive life insurance becomes.
If you have one or more health issues, life insurance could be more expensive, and you might be limited as to what policies you qualify for.
By lifestyle, we mean things like smoking, skydiving, and other activities that increase risk in the eyes of life insurance underwriters.
Only by obtaining all of this information can an agent give you a more accurate quote based on your circumstances.
Know What You Want Your Life Insurance to Accomplish
We use the term life insurance as if it’s an all-encompassing thing. But there are many types of life insurance. There’s term, which comes to an end at some point. There’s whole life, which lasts your entire life (as long as the policy remains in force) and builds cash value. Then there’s indexed universal life insurance (IUL) that offers a death benefit and the potential to accumulate cash value. Under certain conditions, policyholders may be able to access that value through loans, although fees, interest, and tax considerations apply.
The kind of life insurance you desire can change as you reach more life milestones over time. A young homeowner may want a mortgage protection life insurance policy (could be term or whole life) that covers the entire mortgage, a portion of the loan, or the payments for a certain period of time.
If that person gets married and has children, securing greater coverage that includes riders that cover the children might be more fitting.
As the person grows older, a whole life policy that covers final expenses and builds cash value might be the best move.
With everyone having different outcomes in mind for their life insurance, it is important to communicate your goals and what you expect the life policy to do. Your agent can then communicate the pros and cons of each policy before finding a tailored solution to meet your needs.
Only Get Coverage You Can Easily Afford
It’s common for life insurance clients to want the maximum coverage they qualify for. In doing so, they treat the quote process like a game show, where they keep increasing the amount just because it sounds like they’re getting the most value. I’m not trying to make fun of anyone. It’s human nature to want the most bang for your buck, so to speak. Just be careful not to overextend yourself, is all I’m saying.
Keep in mind that when things get tight budget-wise, life insurance is usually the first expense that gets canceled. For this reason, you only want to secure coverage where the premium sits in the background without you having to think about it very much.
A $5,000 policy may not sound as attractive as a $20,000 policy, but the first coverage amount may be enough to bury or cremate you, depending on your final wishes and the area where you reside. Whatever the amount, your family may thank you when the time comes to pay for those expenses.
This is why your agent will ask you about your budget. Keep your policy on the low end of your budget so that you can be sure the money is available when it’s needed most.
A Life Insurance Application Requires Sensitive Information
If the quote you receive from your life insurance agent sounds good, and you’re ready to move forward, the next step is the life insurance application. When attempting to obtain simplified life coverage over the phone with a broker, as is the case with Little Family Security, the application is digital and must be filled out by a licensed life insurance agent.
It should be noted that there are cases where customers can fill out their own forms, but it’s recommended to have a life agent fill out the form to prevent mistakes.
To ensure the information provided on the application is accurate, the agent will ask you questions step-by-step, starting with your full name. Every piece of information gathered helps the insurance company identify you, assess your qualification status, and provide the best service.
For example, your Social Security number goes on the application to accurately identify who you are.
Your address and email address are used for correspondence from the insurance company and allow for the delivery of your life insurance policy packet. The packet contains all the rules and provisions for your policy, so that you are always informed and educated about the coverage you secure.
Your medical information and lifestyle are provided by answering a series of questions. Common questions on an application include: Are you currently in a nursing home? Are you in a wheelchair? Have you ever been diagnosed with a heart attack, stroke, or cancer?
Lifestyle questions ask about smoking, risky behaviors like skydiving and deep-sea diving, and some carriers even ask about your job. Miners and those working with explosives are seen as riskier than someone who sits behind a desk, for example.
The application often asks if you have life insurance currently. You’ll also be required to name one or more beneficiaries. These are the individuals you expect to receive the death benefit when you pass.
At the end of the application, after everything is filled out, the agent will ask for your banking information. This allows for the first and subsequent drafts of your premium. It is recommended to set your policy up with a bank account number and routing number so you don’t have to think about making your payment. The premiums are pulled each month (or quarterly or yearly), making it more likely that your policy will remain in force. Paying with a debit card or credit card is allowed by some carriers, but this is risky because cards expire, and you never want to risk your policy lapsing for any reason.
At Little Family Security, we let prospects know who we are, and who we represent. We are prepared to send prospects our name, license number, national producer number, and a copy of our insurance license. All of this information can be verified by calling the Department of Insurance in your state, giving you more peace of mind.
Be Honest About Your Medical History
While all of the above points are important, this point cannot be stressed enough. Answer the health questions honestly. Lying or embellishing can only hurt you in the end.
Life insurance companies have ways of verifying information provided on applications. Many insurers use MIB, a consumer reporting agency that maintains certain underwriting information from previous insurance applications. Insurers may also review prescription histories or medical records when authorized. Providing inaccurate or incomplete answers can lead to problems with underwriting or future claims, so always answer the questions truthfully and completely.
It’s important to note that having a heart attack in your past, a stroke, or even cancer does not automatically bar you from obtaining coverage. There are lots of carriers and hundreds of products out there. You may not qualify for one carrier, but your agent may have another who will take you with open arms. So, be honest, for your sake, and for the sake of your beneficiaries.
More to that point, never embellish your illnesses. An insurance application is not the time to play up your suffering to gain sympathy. Only answer the questions as asked and do not exaggerate. Only describe the exact ailments, treatments, diagnoses, and medications you have received to the best of your ability.
If everyone I spoke to about life insurance knew these five points, the conversations we engage in would always go much smoother. But some prospects think life insurance is a cookie-cutter approach, and others don’t know what their goals are. Then there are prospects who want more coverage than they can afford, and those that don’t feel comfortable giving sensitive information over the phone. Top it off with people who fib on the application and embellish the health problems they have, and some conversations don’t go the way we expect.
As a licensed life insurance agent, I want what’s best for you and your family. Read these points and remember them the next time you shop for life coverage. You’ll have an easier time doing so, and will be more likely to get the coverage you want according to your needs and budget.
Want affordable life coverage by an independent life insurance agent you can trust? Call (682)802-2276 or visit www.littlefamilysecurity.com to schedule a free, no-obligation consultation.